Cyber Insurance Simplified: Key Terms Every Business Owner Needs to Know
By Joe Erle
Understanding cyber lingo can mean the difference between falling victim to a scam and outsmarting the hackers at their own game. Just ask the CEO of a care home company who found himself at the center of an elaborate “CEO fraud” scheme, which resulted in a loss of over $87,000. 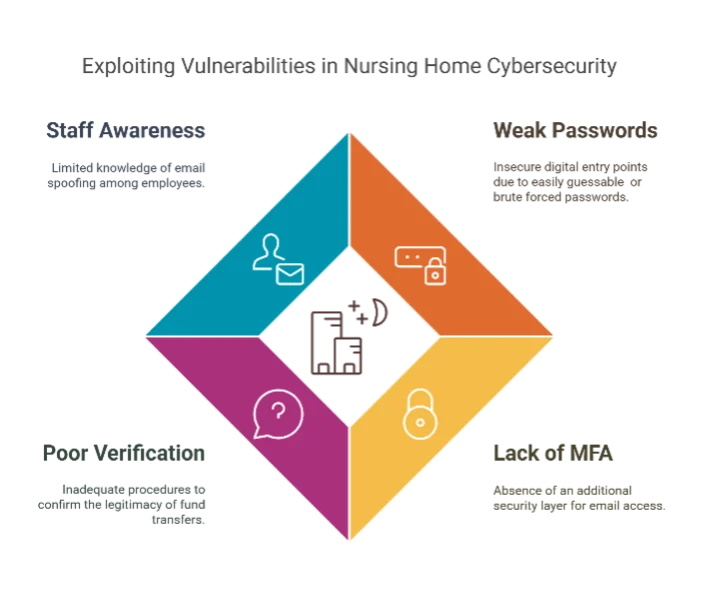
The incident unfolded when a hacker gained access to the CEO’s email account through a brute force attack, exploiting weak password protection and the absence of multi-factor authentication. With the CEO on vacation, the hacker pretended he was the CEO and orchestrated a series of fraudulent fund transfers, leaving the care home reeling from the financial blow.
This cautionary tale underscores a crucial lesson for businesses of all sizes: cybersecurity is not just about firewalls and antivirus software. It’s about understanding human psychology and technology that cybercriminals exploit. From the importance of strong passwords to the need for comprehensive cyber insurance, this incident serves as a wake-up call for organizations to reassess their digital defenses.
When it comes to cybersecurity, the language used can sometimes feel like an entirely different world. Mastering the terminology is essential, particularly for business owners seeking to protect their operations.
Did you know that many cyber insurance endorsements on business owner policies don’t include social engineering? The case study above wouldn’t even be covered if the company purchased the wrong policy.
Why Knowing These Terms Matters
As a cyber broker, I’ve seen firsthand how understanding what you don’t know can be just as valuable as what you do know. Familiarizing yourself with the jargon of the cybersecurity world can empower you to better protect your business and make smarter policy choices.
Taking the time to educate yourself now could save you significant time, money, and stress in the future. If you’ve made it this far, you’re part of the top 1% of executives actively educating themselves on cyber insurance and cybersecurity.
The case study of the nursing home hoax illustrates this point perfectly. In this incident, a care home fell victim to a sophisticated social engineering attack that resulted in a loss of $87,315. The attack exploited several vulnerabilities:
- Weak password protection on the CEO’s email account
- Lack of multi-factor authentication for remote email access
- Insufficient verification procedures for fund transfers
- Limited awareness of email spoofing techniques among staff
Had the care home’s leadership been more familiar with terms like brute force attack, multi-factor authentication, or email spoofing, and how their insurance policy would respond, they might have implemented stronger security measures or bought different coverage.
Additionally, understanding the concept of social engineering could have led to better staff training, potentially preventing the fraudulent transfer of funds. Fortunately, the care home had cybercrime coverage in their cyber insurance policy, which allowed them to recover most of the loss.
This underscores the importance of not only understanding cybersecurity terms but also being familiar with cyber insurance terminology and coverage options. By arming yourself with knowledge of these terms and concepts, you can better assess your organization’s vulnerabilities, implement more effective security measures, and ensure you have the right insurance coverage in place to protect against potential cyber incidents.
Take a moment to explore some essential cyber insurance terms to help safeguard your business. If you have any questions regarding these terms or if you’d like a review of your cyber insurance strategy, reach out to us here are C3 by going to www.c3insurance.com/cyber.
Cyber Insurance Terms Every Business Owner Should Know:
- Adversarial Underwriting: A thorough underwriting process that evaluates your cybersecurity posture, sometimes involving penetration testing and vulnerability scanning.
- Bricking Coverage: Covers the cost of replacing devices rendered inoperable (or “bricked”) by a cyberattack.
- Business Interruption Loss and Extra Expenses: Provides coverage for lost income and additional expenses incurred when a cyber event disrupts your operations.
- Coinsurance: Represents the percentage of a loss that you are responsible for covering.
- Computer Fraud: Covers financial losses due to unauthorized access to your systems.
- Contingent Business Interruption Loss and Extra Expenses: Covers financial losses caused by cyber incidents affecting third-party service providers critical to your business.
- Cryptojacking Coverage: Protects against unauthorized use of your systems to mine cryptocurrency.
- Cyber Incident Response Fund: Covers costs associated with investigating and mitigating a cyber incident, including hiring forensic experts and legal counsel.
- Cyber Incident Response Team: A group of specialists available to assist in managing and resolving cyber incidents effectively.
- Cyber, Privacy, and Network Security Liability: Covers claims arising from data breaches, privacy violations, and network security failures.
- Dependent System Failure: Covers losses caused by system failures of third-party service providers.
- Digital Data Recovery: Helps cover the costs of restoring or recreating digital data lost or damaged due to a cyber event.
- Electronic, Social, and Printed Media Liability: Covers claims related to content published on websites, social media, or other platforms.
- Extended Reporting Period: An optional extension allowing you to report claims after the policy period ends.
- Funds Transfer Fraud: Protects against losses resulting from fraudulent transfers of funds.
- Invoice Manipulation Coverage: Covers losses resulting from hackers altering payment details on invoices. This is sometimes called reverse social engineering.
- Limit of Insurance: The maximum amount the insurer will pay for covered losses.
- Network Extortion: Provides protection against expenses related to cyber extortion threats, including potential ransom payments.
- Payment Card Loss: Provides coverage for fines, penalties, and assessments imposed by payment card companies after a data breach.
- Ransomware Encounter: Offers specific coverage for incidents involving ransomware attacks.
- Regulatory Proceedings: Covers legal expenses and penalties associated with regulatory investigations stemming from cyber incidents.
- Reputational Harm Coverage: Provides protection against losses due to damage to your organization’s reputation after a cyber incident. This often includes hiring public relations experts.
- Retroactive Date: Defines the date from which incidents are covered, often set to “Full Prior Acts” for comprehensive coverage.
- Retention: The amount you must pay before insurance coverage kicks in (similar to a deductible).
- Social Engineering Fraud: Covers losses resulting from employees being tricked into transferring funds or sharing sensitive information.
- Technology Errors & Omissions (E&O): Covers liabilities related to your services as a software or technology provider.
- Telecommunications Fraud: Protects against unauthorized use of your phone or internet services.
- Utility Fraud: Covers losses when hackers illegally use your utilities.
- Voluntary Shutdown Coverage: Covers losses when your organization voluntarily shuts down systems to prevent further damage during a cyberattack.
- Widespread Severe Known Vulnerability Exploit: Protects against incidents arising from the exploitation of widely known security vulnerabilities.
- Widespread Severe Zero-Day Exploit: Provides protection against previously unknown vulnerabilities that attackers exploit.
- Widespread Software Supply Chain Exploit: Covers damages caused by compromised software in the supply chain.
Let’s work together to make American businesses more protected from cybercrime.
Joe Erle, Cyber Group Practice Leader